
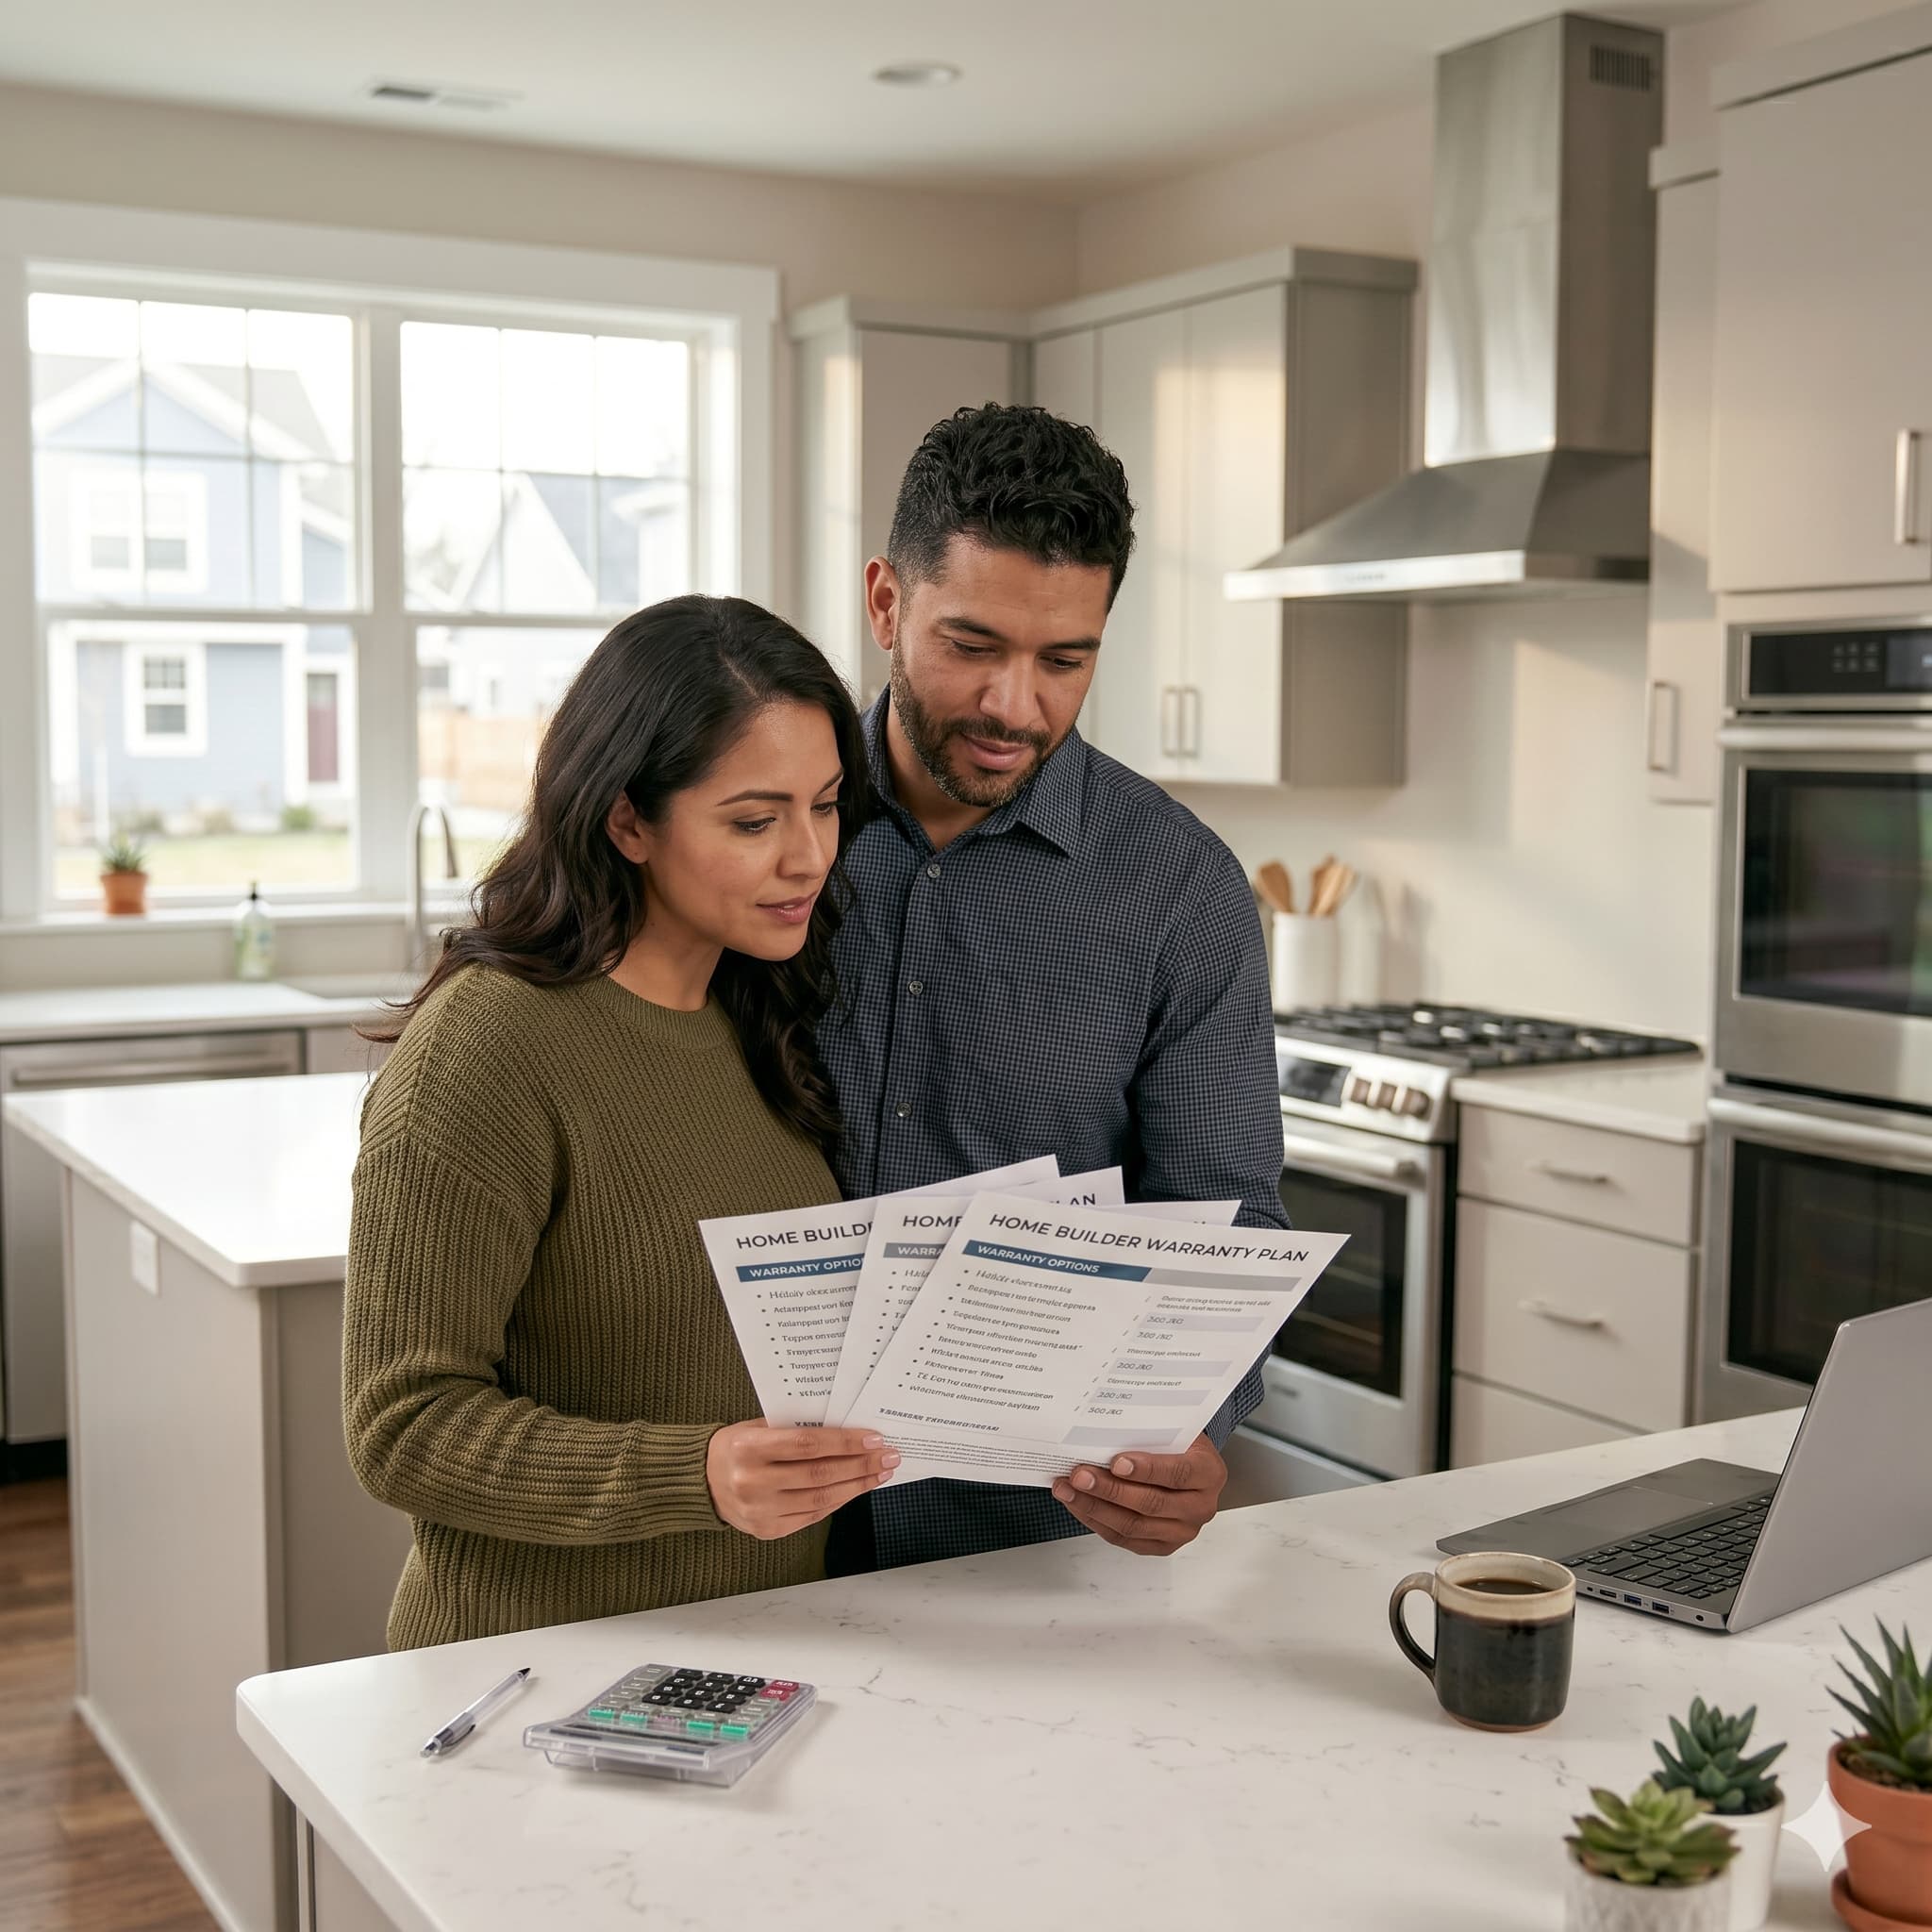
Buying a newly built home can make you feel like major repairs are years away, but new construction does not necessarily mean every problem is covered forever.
Before purchasing a home warranty for new construction, it is important to understand:
- what your builder’s warranty already covers
- how long those protections last, and
- where a separate home warranty may provide additional coverage.
Comparing the two can help you avoid paying for overlapping protection or overlooking important gaps.
Usually, a new construction home buyer assumes the builder warranty covers everything for the first 10 years. The reality is that most builder warranties cover structural issues for 10 years, mechanical systems for two years, and workmanship issues for one year.
What that means is that, by month 13, large portions of the home are no longer covered.
That gap between when builder coverage ends and when manufacturer warranties on individual appliances begin is exactly where home warranties become a relevant decision.
Whether to buy one depends on which gaps you actually face and how comfortable you are absorbing repair costs in the early years.
> Builder warranties typically follow a 1-2-10 structure: one year on workmanship, two years on mechanical systems, and ten years on major structural elements. Knowing exactly when each layer expires is the starting point for any home warranty decision.
A new-construction home already carries manufacturer and builder warranties that overlap with what a third-party plan sells. USA.gov’s home-repair programs page lists legitimate assistance options for repairs neither one covers, and HUD’s home improvements page is a federal baseline worth checking too.
What a Builder Warranty Actually Covers
Most builders provide a structured warranty modeled on the 1-2-10 framework. The exact terms vary, and the warranty itself is a contract, not a regulatory standard.
- Year one typically covers workmanship defects. Misaligned doors, paint defects, drywall cracking from settling, flooring installation issues, cabinet hardware problems. Anything that the builder controlled in construction quality.
- However, through years one through two cover the mechanical systems. HVAC equipment, plumbing systems, electrical systems. Failures that result from defective installation or component failure during normal use are typically covered.
- Finally, years one through ten cover major structural defects. Foundation failures, load-bearing wall issues, roof structure failures. The threshold for what counts as “major structural” is typically high. Aesthetic foundation cracks usually do not qualify; foundation movement that compromises the home’s structural integrity does.
Manufacturer warranties on individual appliances are separate from the builder warranty.
Most major appliances carry a one-year manufacturer warranty, and many have extended warranties available at additional cost.
HVAC equipment often comes with a separate 5-to-10-year manufacturer warranty on the compressor and a shorter warranty on parts and labor.
As a result, you’ve got a layered coverage structure that is difficult to track without a written summary. To avoid this, build the summary early in your ownership and update it as warranties expire.
Why Year Two Is the Critical Decision Point
The most consequential gap appears at month 13, when the workmanship coverage ends but mechanical systems are still covered for another year.
However, at month 25, the bigger gap appears. This is when mechanical coverage ends but the home is now two years old with two years of use on every system.
At this point, this is the window when a home warranty becomes a relevant question. Before month 13, the builder warranty handles most issues.
After month 25, mechanical systems are uncovered by the builder for the first time, and any failures become the homeowner’s responsibility unless covered by remaining manufacturer warranties.
A home warranty starting at month 25 covers the same systems the builder warranty just stopped covering. The premium is essentially insurance against an early-life failure on a system that is still under manufacturer warranty for parts but not for labor or installation.
For homeowners with aging-in-place plans and limited cash reserves for repairs, the home warranty starting at month 25 can make sense as a continuity product.
For homeowners with strong reserves and willingness to self-insure, the manufacturer warranties on most systems make a separate home warranty redundant for the first 5 to 7 years.
When a Home Warranty Is Worth It on New Construction
A home warranty on new construction is most likely to pay off in three specific scenarios.
If the builder went out of business or has a poor track record of honoring warranty claims, a third-party home warranty creates a backstop that does not depend on the builder remaining in business.
This is increasingly common in regional markets where smaller builders close after construction declines.
If you bought from a builder whose mechanical contractors used lower-tier equipment, the systems may fail faster than the manufacturer warranty period suggests.
Lower-tier HVAC systems and water heaters often have shorter usable lives than premium equipment, and the warranty becomes more relevant as a result.
If you have minimal cash reserves and would face genuine hardship from a $4,000 to $8,000 unexpected repair in the home’s third or fourth year, the predictable monthly cost of a home warranty has value as cash-flow protection regardless of whether the math favors it on a pure expected-value basis.
> The decision to buy a home warranty on new construction is rarely about the first two years. It is about years three through seven, when manufacturer warranties have expired on labor and installation but the systems are still relatively young. That window determines the value of the contract.
When You Can Skip the Home Warranty
The home warranty is least likely to make sense in these scenarios.
If your home was built by an established builder with a strong warranty service track record and the major systems came with extended manufacturer warranties of 5 years or more, you have meaningful overlap with what a home warranty would provide.
If you have a healthy emergency fund and the financial flexibility to absorb a major repair without disrupting your budget, the warranty’s primary value, predictable cash flow, has less weight in your decision.
If your home was built with premium equipment and you are committed to documenting maintenance carefully, the failure risk in the early years is genuinely low and the warranty’s expected payout is correspondingly small.
For more on whether home warranties are worth their cost across different home situations, see Is a Home Warranty Worth It on a Resale Home? and What a Home Warranty Actually Covers.
Questions Homeowners Ask
- Is a home warranty worth it on a resale home?
- What does a home warranty actually cover?
- How are home warranty claims processed?
Use this decision checklist
| Coverage layer | What to verify in writing | Decision point |
|---|---|---|
| Builder warranty | Which workmanship, systems, and structural items are covered and for how long? | Use the builder process first while that layer is active. |
| Manufacturer warranty | Which appliances or equipment have separate coverage? | Check the product warranty before paying a service contract fee. |
| Service contract | What exclusions, caps, service fees, and contractor rules apply? | Buy only if the remaining gap is worth the premium and claim friction. |
| Your records | Where are inspections, repair requests, invoices, and warranty contacts stored? | Create the record before a deadline or claim dispute arrives. |
For the underlying safety and consumer-protection rules, see the FTC’s guide to new-home builder warranties, HUD’s new-construction warranty requirement for FHA-insured financing.